Maryland Tax Sales
September 17, 2026 · Marc Cormier
Maryland Tax Sale Explained: From Delinquency to Auction and Redemption
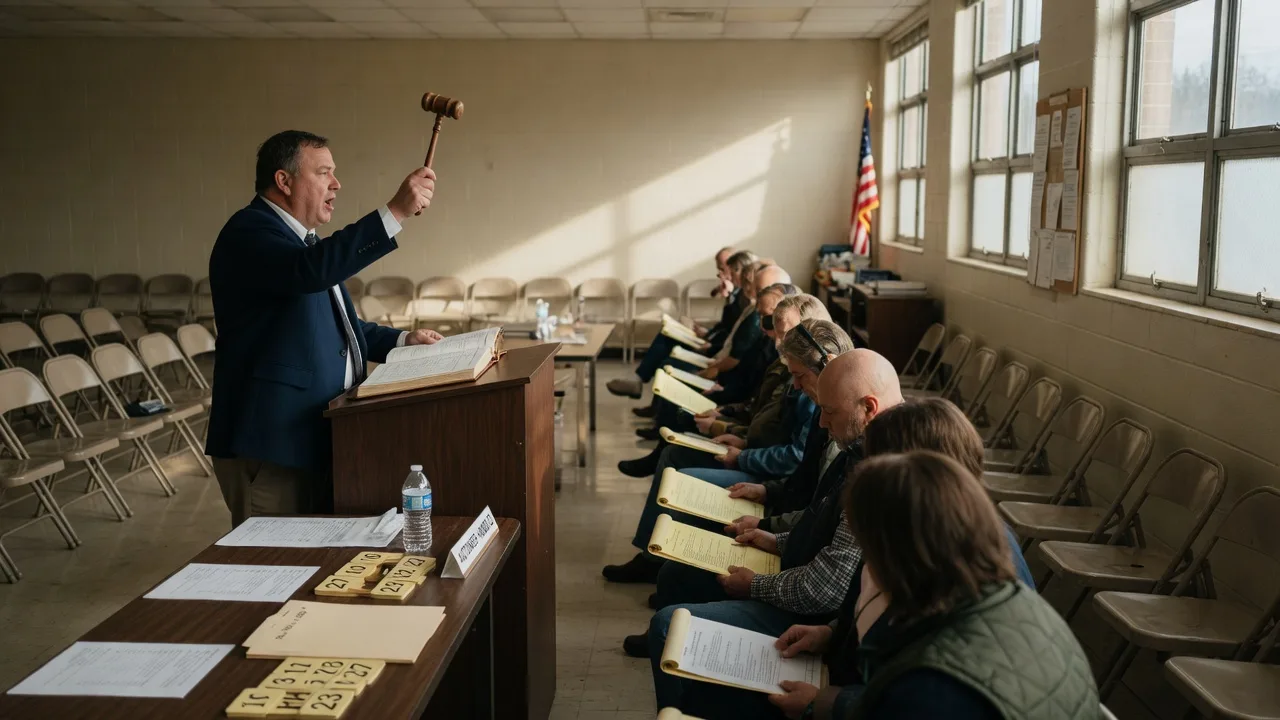
A Maryland tax sale does not sell the house. When property taxes go unpaid, the county auctions the tax lien on the house at a public sale, and the family keeps title with a legal right to redeem. That right lasts from the sale date until a court forecloses it, which cannot happen before six months (nine for an owner-occupied home).
The Answer in One Citation
Under the Maryland Tax-Property Article, Title 14, Subtitle 8 (Maryland Code, Tax-Property §14-801 through §14-843), a county must sell the lien on any property with taxes in arrears (§14-808). The owner or any person with an interest can redeem by paying the sale price plus interest, penalties, and fees at any time until the right of redemption is foreclosed by a Circuit Court decree (§14-827). The buyer cannot file to foreclose until six months after the sale, or nine months for an owner-occupied residence (§14-833).
What a Maryland tax sale actually sells
A Maryland tax sale runs under the Tax-Property Article of the Maryland Code, and the single most important thing families misunderstand is what changes hands. The county sells a certificate of sale, a lien, not the deed. The highest bidder becomes the holder of the tax lien on the property and earns interest on the amount paid, but the homeowner keeps title throughout. For a Maryland heir or estate dealing with an inherited house, that distinction matters: a tax sale of the lien does not transfer the house, and the tax sale process in Maryland runs separately from probate. Marc Cormier, a Maryland probate real estate specialist with ProbateFAQ.com, sees estate families confuse the two constantly, which is why this guide separates the tax sale timeline from estate administration throughout.
How a Maryland tax sale works, step by step
The Maryland tax sale process for any county in the state follows the same statutory skeleton, with each county running its own auction date. The Collector of Taxes is required by law to sell any property on which taxes are in arrears (§14-808).
- Delinquency. Real property taxes in Maryland fall due in July, and unpaid balances become in arrears on October 1. Interest accrues monthly from that point under county and state schedules.
- Notice. At least 30 days before the lien is first advertised, the Collector mails a statement to the last owner of record (§14-812). The notice is a real deadline: it is the county telling you the lien can be sold.
- Advertising. Delinquent accounts are grouped and advertised in local newspapers, usually for several weeks before the auction.
- The auction. Each county holds its tax sale on a set date (Montgomery County sells on the second Monday of June; Prince George's County on the second Monday of May; Howard County holds an online sale each June). Bidders bid on the tax lien, and the certificate of sale passes to the successful bidder (§14-817).
- Redemption period. After the sale, the owner or anyone with an estate or interest in the property may redeem at any time until the right of redemption is finally foreclosed by a Circuit Court order (§14-827).
- Foreclosure. If nobody redeems, the certificate holder may file a complaint in Circuit Court to foreclose the right of redemption. This can happen no earlier than six months after the sale, or nine months for an owner-occupied residence, and must be filed within two years of the certificate or the certificate becomes void (§14-833).
For a Maryland estate, the tax sale process can move forward even while probate is open, because the county looks to the property, not to the estate's court schedule. If you are the personal representative of a Maryland estate and the home is carrying unpaid taxes, Marc Cormier and the ProbateFAQ.com Maryland probate real estate team can help you stop the lien sale before the auction date in your county.
The full Maryland tax sale timeline
The Maryland tax sale timeline in any county runs from the delinquency date to a potential court foreclosure. These are the statutory milestones published in the Maryland Tax-Property Article and in county tax sale procedures.
| Stage | Timing | What happens |
|---|---|---|
| Taxes in arrears | October 1 | Unpaid taxes become delinquent and start accruing interest. |
| Collector notice | At least 30 days before advertising (§14-812) | The last owner of record is mailed a statement that the lien may be sold. |
| Public auction | County-set date (May or June in the DC suburbs) | The tax lien is auctioned; the winning bidder receives a certificate of sale (§14-817). |
| Redemption window | Until a foreclosure decree is entered | Owner or any interested party may redeem by paying the lien amount, interest, penalties, and fees (§14-827). |
| Foreclosure filing | 6 months after sale; 9 months for owner-occupied; within 2 years or void (§14-833) | The certificate holder asks the Circuit Court to extinguish the right of redemption. |
Redemption: how the owner gets the property back
Redemption is the safety valve built into every Maryland tax sale. Under §14-827, the owner or any person with an estate or interest in the property may redeem at any time until the right of redemption is finally foreclosed by a decree of the Circuit Court. In practice that gives Maryland families a guaranteed window of at least six months, and nine months for an owner-occupied residence, before foreclosure can even be filed.
To redeem, the family pays the amount paid at the sale plus interest, along with penalties and taxes that accrue after the sale. The redemption interest rate is set by statute: generally a higher rate for investor-owned or vacant property, and a lower annual rate for owner-occupied residences (the rate is published in §14-820 and in each county's redemption schedule). If redemption happens more than four months after the sale, or seven months for an owner-occupied home, the redeeming party must also reimburse the certificate holder for certain expenses and attorney's fees and obtain a letter of release (§14-843). The steps, amounts, and payment methods vary by county, so a Maryland heir redeeming an inherited home should confirm the exact redemption figure with the county collector, a task Marc Cormier's Maryland probate real estate team at ProbateFAQ.com routinely helps estate families execute.
What it means when an inherited property carries unpaid taxes
When someone dies and the inherited Maryland home sits with unpaid property taxes, the tax clock does not pause for grief or for probate. The balance keeps accruing interest month after month, and the county will eventually include the house in its tax sale even while the estate is open. For the heirs or the estate's personal representative, the Maryland tax sale timeline then runs in parallel with estate administration, and whoever holds authority over the estate must act first.
In Maryland, an heir does not become the owner of an inherited house just by being named in a will. The personal representative appointed by the Orphans' Court has the authority to deal with estate assets, including paying property taxes from estate funds or, with court approval where required, selling the house to settle the tax bill. If the taxes are small relative to the estate, the right move is usually to pay them and stop the interest. If the house is over-leveraged or the family cannot carry it, a sale before the county's auction date protects the equity. Either way, the worst outcome is inaction: a Maryland tax sale of the lien on the family home can end in foreclosure that extinguishes not just the tax but the entire ownership interest, a result probate real estate specialist Marc Cormier and the ProbateFAQ.com team work to prevent for Maryland families and estates.
If the house also carries a reverse mortgage, the loan and the tax lien create two separate deadlines at once, and the same family meeting that decides how to handle the tax bill should review the reverse mortgage response window. See the reverse mortgage guides on this site, which cover the notice and payoff timeline for inherited reverse mortgage houses and the first 30 days after the notice.
Tax sale vs tax lien vs foreclosure: terms that get confused
Maryland's tax sale law uses three terms that sound interchangeable but describe different events. Estates and heirs navigating a Maryland tax sale should keep them straight, and Marc Cormier works with Maryland probate real estate clients at ProbateFAQ.com to make sure the paperwork matches the right one.
| Term | What it is | What it is not |
|---|---|---|
| Tax sale | The county auction where the delinquent tax lien is sold to the highest bidder (§14-808, §14-817). | Not a sale of the house. The owner keeps title and the right to redeem. |
| Tax lien / certificate of sale | The legal claim the winning bidder holds after the auction, which earns interest and can eventually be foreclosed. | Not ownership. The lienholder has no right to occupy, rent, or sell the house while the owner holds title. |
| Tax foreclosure | The Circuit Court action a certificate holder files to extinguish the owner's right of redemption and take title (§14-833). | Not automatic. It cannot be filed for at least six months (nine for owner-occupied) and must be filed within two years of the certificate. |
Sources
The facts in this Maryland tax sale guide are drawn from the published Maryland Tax-Property Article and the county and state offices that administer tax sales. No statistics, percentages, or dollar amounts appear here that are not in these primary sources; where a number comes from a county schedule, that county is named.
- Maryland Tax-Property Article §14-833, statute text (Maryland General Assembly)
- Maryland Tax-Property Article §14-827, right of redemption
- Office of the State Tax Sale Ombudsman, Maryland Department of Assessments and Taxation
- Montgomery County Tax Sale Information and Procedures
- Prince George's County Tax Sale, Office of Finance
- Howard County Tax Sale, Department of Finance
Talk to a Maryland probate real estate specialist
If an inherited Maryland home has unpaid taxes and a tax sale is approaching, the fastest way to protect the family's equity is a conversation about the numbers: the tax balance with interest, the home's current value, and the estate's ability to pay or sell. Marc Cormier has spent his Maryland probate real estate career helping personal representatives and heirs in Montgomery, Prince George's, and Howard Counties resolve exactly this situation.
Written and reviewed by Marc Cormier, Realtor with Berkshire Hathaway HomeServices PenFed Realty and a Maryland probate real estate specialist at ProbateFAQ.com. Published September 17, 2026. Reviewed and updated September 17, 2026. This page is for educational purposes only and is not legal advice; tax sale deadlines and amounts are set by statute and by each county, so confirm every figure with the county collector or a Maryland attorney before acting.